
Regular savings plan in the Altersvorsorgedepot: save into ETFs automatically every month
A regular savings plan is the natural heart of a good Altersvorsorgedepot: you automatically pay in a fixed amount every monthwhich is invested directly in ETFs or funds. Start small, set it up once, benefit for years.
Table of contents
What is a regular savings plan?
A regular savings plan is a standing order that pays not into an instant-access savings account but directly into securities You set the amount, the execution day and the savings target (ETF, fund), and the provider then buys automatically at the specified time.
How does a regular savings plan work in the Altersvorsorgedepot?
- You open a certified Altersvorsorgedepot.
- You choose one or more ETFs / funds.
- You set the savings plan amount (typically €25, €50, €100, €150).
- The direct debit is executed every month.
- Allowances are added automatically and invested as well.
Why do I even need a regular savings plan?
Saving automatically every month is the simplest way to put compound interest to work for you.
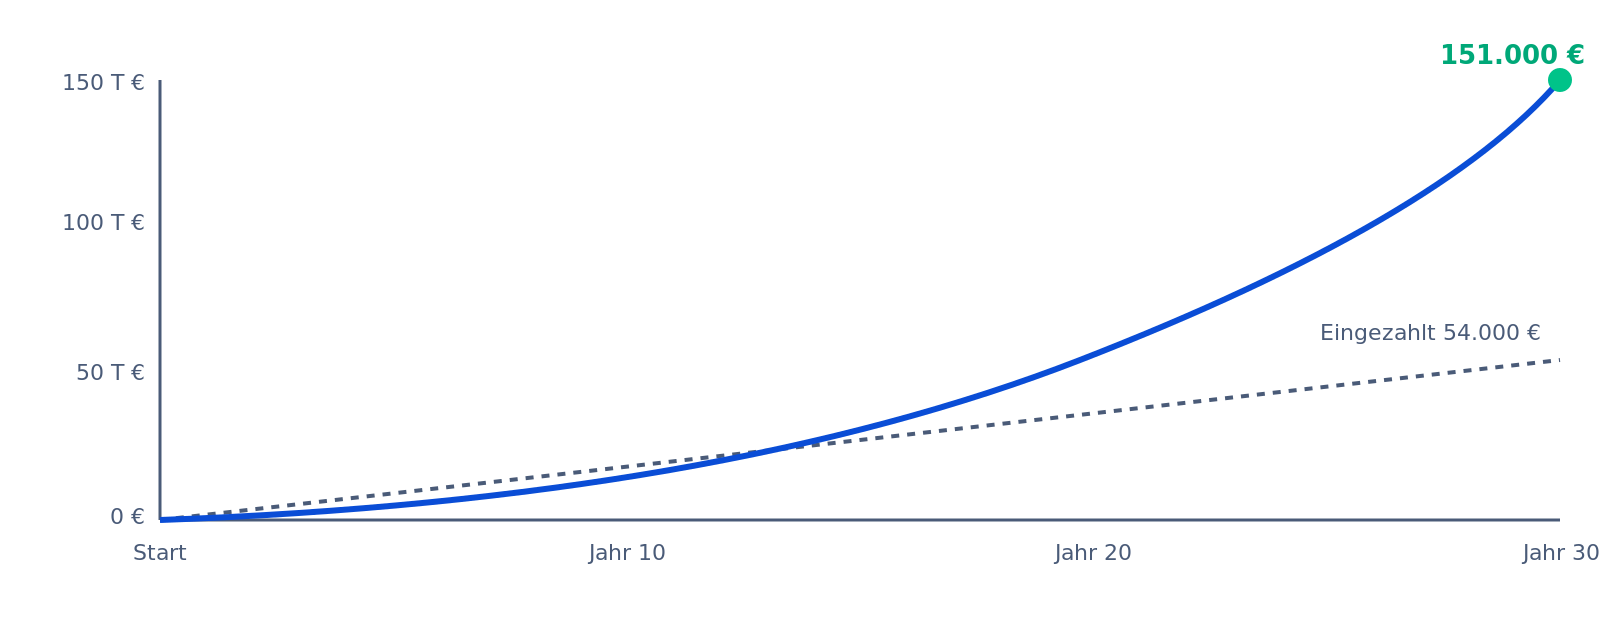
Growth of a regular savings plan over 30 years (€150/month)
Cost averaging: the average beats timing
Because you always pay in the same amount, when prices are low you automatically buy more units, and when prices are high fewer. Over a long period this produces a favorable average price, and you do not have to guess the perfect entry point.
How much does it add up to in the end?
| Monthly contribution | Term | Return p.a. | Final balance |
|---|---|---|---|
| €100 | 20 years | 6% | ~€46,000 |
| €150 | 30 years | 6% | ~€151,000 |
| €200 | 35 years | 7% | ~€360,000 |
| €300 | 40 years | 7% | ~€790,000 |
Excluding allowances and taxes. With allowances you get up to €540 a year plus child allowances on top.
Practical tips for your regular savings plan
- Start early: every extra month multiplies the compounding effect.
- Increase the amount with your salary: with every pay rise, put 1% more into the savings plan.
- At least €150/month: use the full basic allowance.
- Keep the ETF selection small: 1–2 broadly diversified ETFs are enough.
- Do not stop the savings plan: stick with it even in crashes, that is the whole advantage.
Practical examples of savings plans
Beginner Lukas, 25, €50/month. He secures the full 50% allowance on the first €360. He increases the amount every 2 years until he reaches €150/month.
Late starter Petra, 50, €300/month. A high contribution, quickly catching up on the pension gap. At a 5% return over 17 years, around €100,000 final balance.
Frequently asked questions about the regular savings plan
Can I pause the savings plan?
Yes, at any time online and free of charge. But make sure you pay in at least the minimum amount per year to secure the full allowance.
Can I have several savings plans in the same securities account?
Yes, many providers allow several parallel savings plans, e.g. a world ETF and an emerging markets ETF.
What happens if the account is empty?
The direct debit bounces and the provider informs you. If this happens repeatedly, the savings plan can be stopped automatically.
Regular savings plan or one-off payment?
A regular savings plan is the norm. One-off payments are possible and count toward the €1,800 limit for the year.
How often should I review the amount?
Once a year, ideally after a pay rise.
Can I choose the execution day?
Yes, the 1st, the 15th or the end of the month are common. It has only a minimal effect on the final balance.
How high should the contribution be?
Even €25 to €50 a month is enough to build six-figure sums over the long term.
Last updated: June 2026.
Keep calculating and reading
Altersvorsorgedepot calculator Plus — calculate the subsidy, tax advantage and final balance for your own situation.
All terms at a glance: Glossary from A to Z.
Official sources and further information
- Federal Ministry of Finance, FAQ on the reform of private retirement provision
- German federal government, private retirement provision reform
- German Bundestag, resolution on the Altersvorsorgedepot (calendar week 13/2026)
- Bundestag printed paper 21/4088 (PDF)
- Deutsche Rentenversicherung, reform announcement
- Stiftung Warentest, Altersvorsorgedepot
- Verbraucherzentrale, the new Altersvorsorgedepot: opportunity or sales trap?