The Altersvorsorgedepot: why the Riester successor is real progress
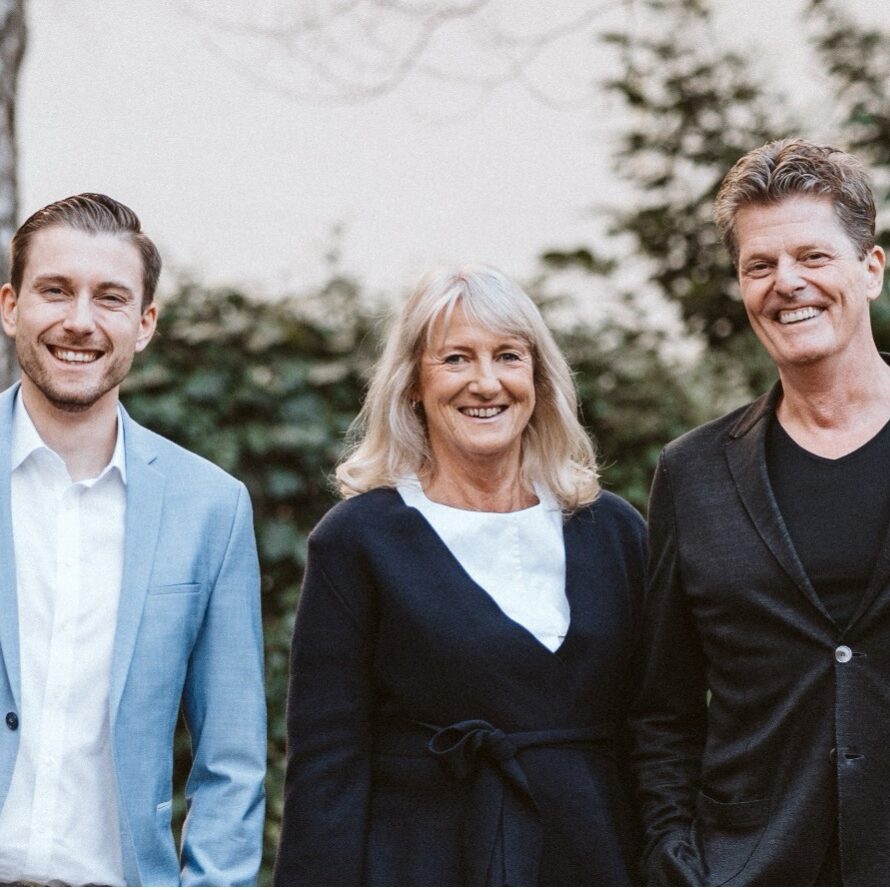
Leadership trio: Christoph Braun, Angelika Hofmann, Josef Hiergeist
A contribution from advisory practice – for private individuals, families and the self-employed
by Christoph Braun, Managing Director of Hofmann & Hiergeist Gesellschaft für Finanzberatung und Vermögensbetreuung mbH
Hardly any topic has come up as often in my advisory conversations over the past months as the question: “Is Riester still worth it at all – or should I wait for the new Altersvorsorgedepot?” The answer is now clear, because the reform is a done deal. The Bundestag passed it on 27 March 2026, the Bundesrat approved it on 8 May 2026, and from 1 January 2027 the new system will be available to all citizens. Time to take stock from an advisor’s point of view of what is changing – and why I now recommend to many of my clients that they look seriously at switching.
Öffnet den Artikel mit fertigem Prompt in:
ChatGPT Claude Perplexity Google AI Mode GrokEs werden keine Daten an Dritte übertragen, bevor Sie klicken.
Why Riester reached its limits
Riester was a good idea in 2002: a state-subsidized, funded supplement to the statutory pension, made attractive for low earners and families with children through allowances. In practice, however, the product suffered from three structural problems that I kept running into in advisory work:
- High costs, with acquisition, administration and guarantee costs eating up a large part of the return.
- The 100 percent contribution guarantee, which forced providers into a very defensive investment style heavily weighted towards interest-bearing products – with correspondingly meager earnings in the zero-interest era.
- A narrow circle of people eligible for subsidy: the self-employed, freelancers and business owners were effectively excluded from the subsidy, even though they in particular often have no occupational pension and no compulsory insurance in the statutory pension system.
The result: stagnating sales figures and a product that I have been able to recommend with a clear conscience less and less often in recent years.
What the Altersvorsorgedepot does differently
With the Retirement Provision Reform Act, a new core product is emerging: the Altersvorsorgedepot. Unlike with classic Riester contracts, money here is invested directly on the capital markets without a contribution guarantee – in stocks, funds and ETFs that appear on a positive list defined by law. Anyone who prefers a safety-oriented approach is not forced to switch: guarantee products with an 80 or 100 percent contribution guarantee remain eligible for subsidy and therefore continue to exist alongside.
For everyone who finds it hard to choose between the offers, there will also be a “standard retirement securities account” (Standarddepot Altersvorsorge) – a simple, low-cost benchmark product that every provider has to offer and whose costs are capped by law at 1.0 percent per year. In my view this is the real masterstroke of the reform: a reference product like this also forces the remaining providers to move on costs, because customers now have a genuine yardstick for comparison.
What this means in concrete terms for my three client groups
Private individuals without children
What convinces me most here is the new allowance logic. Anyone who so far had no Riester contract because the return after costs looked too meager to them now gets, with the standard securities account, a low-cost, return-oriented and still state-subsidized instrument for the first time. The combination of a cost cap and a performance-related basic allowance – 50 cents for every euro paid in, up to an annual contribution of €360 – rewards active saving far more than the rigid Riester flat rate of €175.
Families
For parents, the new child allowance is the biggest step forward: the full €300 per child per year will in future be available from a monthly contribution of just €25 – until now a considerably higher own contribution was needed for this. Families with several children and limited monthly leeway in particular benefit disproportionately here. In advisory sessions I now deliberately run the comparison, because for households with many children and low incomes it can in individual cases still be worth staying in the old Riester system – a point I always work through individually before advising a switch.
The self-employed and freelancers
For me this is the real innovation of the reform: for the first time, government subsidy is opening up to the self-employed, freelancers and business owners, who until now were practically excluded from Riester. This group in particular often has neither an occupational pension nor any firm entitlements from the statutory pension insurance – the Altersvorsorgedepot closes a genuine retirement provision gap here and should, in my view, become a firm part of every retirement plan for entrepreneurs.
What happens to existing Riester contracts
An important point that often causes uncertainty in advisory conversations: nobody has to take action. Existing Riester contracts continue unchanged with grandfathering; there is neither automatic termination nor forced conversion. Anyone who wants to can voluntarily switch to an Altersvorsorgedepot without having to repay subsidy already received – although switching, acquisition and distribution costs may arise, which I weigh against the advantages of the new subsidy in every individual case. New contracts under the old Riester model are only possible until 31 December 2026.
My conclusion from advisory practice
I am rarely euphoric when legislators reform an existing subsidy system – too often it becomes more complicated rather than simpler. With the Altersvorsorgedepot my impression is different: the cost cap creates genuine comparability, the return-oriented investment in stocks and ETFs opens up realistic return opportunities over long savings periods, and opening the system up to the self-employed closes a gap that I have seen in advisory work for years as one of the biggest provision problems facing this professional group.
Even so, the same applies as to every retirement provision decision: blanket recommendations are out of place. Anyone with a high need for security should not dismiss the guarantee variants, which remain available, too hastily. Anyone who already has a running Riester contract should have the individual switching costs and their personal family and income situation calculated precisely before switching. And anyone who has no contract yet but wants to start providing for retirement as early as 2026 should weigh up whether one last Riester contract before the end of the year still makes sense, or whether it is worth waiting for the launch on 1 January 2027.
The reform offers considerably better conditions than the previous system, but the best solution is always the one that fits your individual circumstances.
What does the Altersvorsorgedepot give you?
Subsidy, tax advantage and potential account value in under a minute, using your own figures.
About the expert
Christoph Braun
Managing Director, Hofmann & Hiergeist GmbH
Christoph Braun is Managing Director of Hofmann & Hiergeist Gesellschaft für Finanzberatung und Vermögensbetreuung mbH, holds a master’s degree in business administration and has more than fifteen years of experience in the finance and insurance industry. Together with the company’s founders, Ms. Hofmann and Mr. Hiergeist, he shapes the strategic direction and further development of Hofmann & Hiergeist GmbH. Together with his team he stands for personal, owner-managed and all-round 360° advice. From protecting the family through building wealth for high-net-worth private clients and entrepreneurs to retirement planning, the company supports its clients with a clear plan for their financial future – holistic, sustainable and always on equal terms.