
Basic allowance in the Altersvorsorgedepot: up to €540 per year from the state
The basic allowance is the direct state subsidy that savers receive in an Altersvorsorgedepot account. It replaces the rigid €175 allowance of the Riester pension and, from 2027, is proportional to your own contribution.
Table of contents
What is the basic allowance?
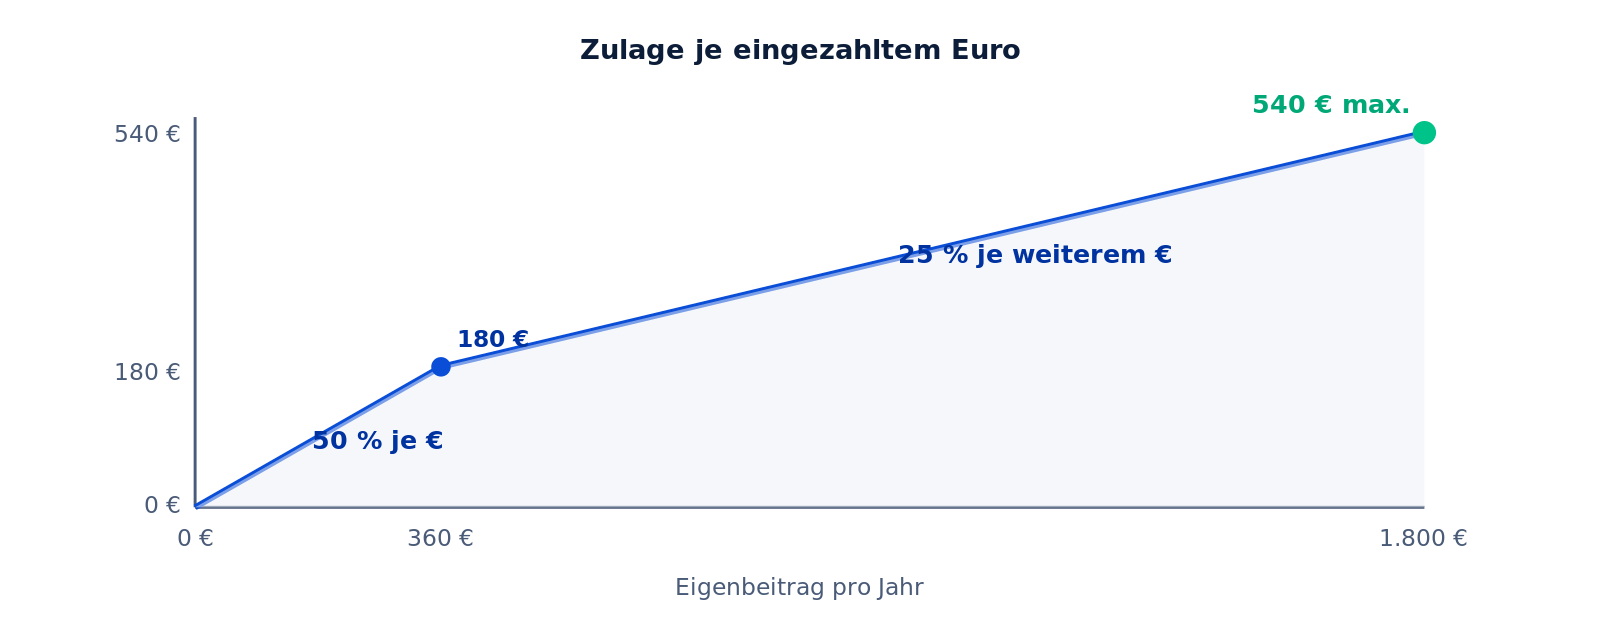
The basic allowance is a cash subsidy from the state on the annual contributions into a certified Altersvorsorgedepot. It is credited directly to the securities account and invested immediately. Unlike Riester, there is no longer a fixed minimum base amount, but a percentage subsidy per euro contributed.
Subsidy ladder: allowance per euro contributed
Who is entitled to the basic allowance?
- People with compulsory cover in the statutory pension insurance
- Civil servants, judges and career soldiers
- Self-employed people and freelancers (new from 2027)
- Compulsory members of professional pension schemes
- Recipients of unemployment benefit I / sickness benefit
Spouses can each open their own securities account and thus receive the allowance twice over.
How much do I have to contribute for the full subsidy?
Anyone contributing €1,800 per year collects the full basic allowance. With a smaller own contribution, correspondingly less.
When does the new basic allowance apply?
From 1 January 2027. For existing Riester contracts the old allowance (up to €175 per year) remains in place as long as the contract is continued. Anyone switching to an Altersvorsorgedepot automatically falls under the new subsidy.
How does the basic allowance work?
| Contribution / year | Allowance rate | Allowance | Subsidy rate |
|---|---|---|---|
| €120 | 50% | €60 | 50% |
| €360 | 50% | €180 | 50% |
| €600 | 50% + 25% | €180 + €60 = €240 | 40% |
| €1,200 | 50% + 25% | €180 + €210 = €390 | 33% |
| €1,800 | 50% + 25% | €180 + €360 = €540 | 30% |
The provider applies for the allowance once via a permanent allowance application to the Central Allowance Office for Retirement Assets (ZfA). Payment is made annually in the following year.
How much can I get out of it?
In the best case: €540 basic allowance + €300 per child + €200 career starter bonus. A family with two children in which both parents contribute €1,800 per year collects up to €1,680 in allowances per year in total; over 30 years of working life that adds up to more than €50,000 in pure subsidy capital, which earns a return on top.
How much do you get? Calculate your personal basic allowance and tax saving in the AVD calculator.
Why was the allowance reformed?
The old Riester allowance of €175 had not been raised for years and was too low relative to rising living costs. The 4% calculation was also complicated, and many savers missed out on the full allowance. The new proportional subsidy is easier to understand, higher and rises automatically with your own contribution.
Model calculations from everyday life
Lara, 24, starting her career, €32,000 gross. She contributes €100/month (€1,200/year) to her securities account. Allowance: 50% on the first €360 (€180) + 25% on €840 (€210) = €390 basic allowance. Plus a one-off career starter bonus of €200. Subsidy rate in the first year: 49%.
Murat, 39, programmer, €75,000 gross. He contributes the maximum amount of €1,800/year. Full basic allowance €540. At his marginal tax rate of 38% the special expenses deduction is more favorable, with a tax saving of €684, and the tax office selects it automatically (more-favourable-treatment check).
Christine, 36, single parent, 2 children, €38,000 gross. She contributes €50/month (€600/year). Basic allowance: €180 (50% on €360) + €60 (25% on €240) = €240. Plus €600 child allowance (2 × €300) = €840 in government subsidy on €600 of own contribution (subsidy rate 140%).
Spouses: making the most of the double allowance
Married couples can benefit twice if both open their own Altersvorsorgedepot. The non-working spouse can also be entitled to the basic allowance; the requirement is an own minimum contribution (the so-called “minimum base amount”) of €120 per year and a subsidy-eligible main earner. This secures the family 2 × €540 = up to €1,080 in basic allowance.
Minimum contribution and base rule
For the provider to be able to apply to the ZfA for the allowance at all, you must contribute at least €120 per year (€10/month) out of your own pocket. Anyone below this threshold loses the allowance entirely, including the child allowance. The ZfA checks this automatically every year via the provider’s data report.
When is the allowance credited?
The allowance office (ZfA) checks retroactively each year. The allowance for contribution year 2027 is typically credited to the securities account in the second half of 2028. Anyone who has issued a permanent allowance application does not have to do anything further, not even in their tax return.
Frequently asked questions about the basic allowance
What happens if I contribute less than €360?
You receive exactly 50% of your own contribution as an allowance, but of course correspondingly less.
Do I get an allowance without contributing?
No. At least €120 minimum base contribution per year has to be paid in to secure the full allowance.
Is the basic allowance income?
No. It is not treated as income for tax purposes, but on payout it is taxed together with the securities account (deferred taxation).
Is the basic allowance worthwhile for higher earners too?
Often the bigger lever is the special expenses deduction. The tax office checks this automatically via the more-favourable-treatment check.
What happens if I become unemployed?
While receiving unemployment benefit I you remain eligible for the subsidy. On moving to Bürgergeld (German basic income support), eligibility can be restricted, but the allowance is retained for contributions already made.
Can I claim allowances retroactively?
Yes, up to two years retroactively via the provider. Anyone who has issued a permanent allowance application does not have to do anything; the ZfA retrieves the data automatically.
Do contributions have to be made evenly?
No. You can also pay in once a year or irregularly. All that matters is that €1,800 is reached by the end of the year in order to receive the full allowance.
What if I move?
Within the EU/EEA the subsidy is retained. Moving to a country outside the EU can trigger repayment of the allowances.
Can spouses get more out of it?
Married couples double the allowance if both open their own securities account.
As of June 2026. Sources: BMF, German federal government, Bundestag.
Keep calculating and reading
Altersvorsorgedepot calculator Plus — calculate the subsidy, tax advantage and final balance for your own situation.
- minimum own contribution
- Günstigerprüfung (more-favourable-treatment check)
- permanent allowance application
Related content: Altersvorsorgedepot for low earners.
All terms at a glance: Glossary from A to Z.
Official sources and further information
- Federal Ministry of Finance, FAQ on the reform of private retirement provision
- German federal government, private retirement provision reform
- German Bundestag, resolution on the Altersvorsorgedepot (calendar week 13/2026)
- Bundestag printed paper 21/4088 (PDF)
- Deutsche Rentenversicherung, reform announcement
- Stiftung Warentest, Altersvorsorgedepot
- Verbraucherzentrale, the new Altersvorsorgedepot: opportunity or sales trap?